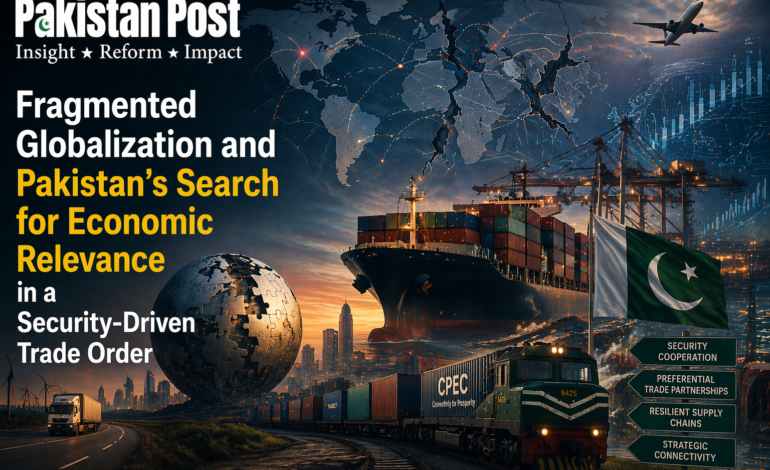
Fragmented Globalization and Pakistan’s Search for Economic Relevance in a Security-Driven Trade Order

The global trading system that once revolved around the logic of efficiency, comparative advantage, and frictionless capital movement is undergoing a structural transformation that is neither cyclical nor temporary. It is increasingly being reorganized around strategic trust, geopolitical alignment, and security considerations. In this emerging architecture of fragmentation, supply chains are no longer built to minimize cost alone, but to minimize risk. The result is a world economy dividing itself into competing blocs, where access to technology, capital, and markets is filtered through political compatibility rather than purely economic rationale. For countries like Pakistan, positioned at the crossroads of Asia, the Middle East, and Eurasia, this transition presents both a narrowing of traditional options and an opening for selective strategic repositioning.
Pakistan’s economic model over the past two decades has been heavily dependent on external inflows, export concentration in low-value textiles, and integration into Western consumer markets through intermediary supply chains. However, the emergence of geoeconomic fragmentation accelerated by US–China strategic rivalry, pandemic-era disruptions, sanctions regimes, and the reshoring of critical industries has begun to reshape the very corridors through which Pakistan historically accessed global demand. The most visible manifestation of this shift is the reconfiguration of global manufacturing away from China-centric dependence toward diversified production hubs in Southeast Asia, Mexico, Eastern Europe, and selectively in South Asia. In this reordering, Pakistan has not yet emerged as a primary beneficiary, despite its geographic proximity to key production networks and its strategic connectivity projects.
The China–Pakistan Economic Corridor, once projected as a transformative bridge between western China and global maritime routes, now sits at an inflection point shaped by this broader fragmentation. Initially conceived in an era of globalization optimism, CPEC’s foundational logic was anchored in connectivity-driven growth, energy infrastructure expansion, and industrial relocation from China’s coastal provinces to lower-cost environments. Yet the global environment in which CPEC was designed has shifted significantly. Chinese firms themselves are now navigating dual pressures: maintaining global market access while insulating critical supply chains from geopolitical exposure. This has made outward industrial relocation more selective, more security-sensitive, and more regionally constrained than originally anticipated.
As a result, Pakistan’s expectation of large-scale manufacturing relocation under CPEC has faced structural delays. The global shift toward “China plus one” strategies has benefited countries with stronger governance predictability, export facilitation systems, and regulatory continuity. While Pakistan retains geographic advantage and political alignment with Beijing, it continues to face constraints in energy pricing stability, tax predictability, and logistics efficiency. In a fragmented global system, these microeconomic frictions become macroeconomic barriers. Investors no longer evaluate location solely on cost; they assess resilience, compliance risk, and geopolitical exposure.
At the same time, the global supply chain is increasingly defined by strategic segmentation. Critical minerals, semiconductors, pharmaceuticals, and energy technologies are being reorganized into trusted networks. This has elevated countries with institutional alignment to major power blocs. Pakistan’s position remains complex in this regard. It is strategically aligned with China, maintains functional ties with Western financial institutions, and is economically intertwined with Gulf capital markets. This multi-alignment offers diplomatic flexibility but complicates economic positioning, particularly when supply chains require clear geopolitical anchoring.
Export dynamics reflect this ambiguity. Pakistan’s export basket remains heavily concentrated in textiles and low-value manufacturing, sectors that are increasingly subject to automation, sustainability compliance requirements, and tariff rebalancing in importing countries. In a fragmented global economy, value-added exports in electronics, processed agriculture, and digital services are becoming more critical. Yet Pakistan’s industrial base has struggled to transition upward due to persistent energy constraints, limited research and development investment, and weak integration into global production networks beyond raw material supply chains.
Foreign direct investment flows further illustrate the implications of fragmentation. Global capital is no longer distributed evenly across emerging markets based on growth potential alone. Instead, investment decisions are increasingly shaped by geopolitical screening mechanisms, regulatory transparency, and long-term supply chain integration potential. Countries in Southeast Asia have attracted significant inflows due to their ability to integrate into diversified manufacturing ecosystems. Pakistan, despite periodic investment announcements, has not yet achieved sustained inflow momentum at scale. The perception of macroeconomic volatility, coupled with recurring balance-of-payments pressures, continues to weigh on investor confidence.
However, fragmentation is not solely a constraint; it also creates selective openings. As global firms diversify away from concentrated production hubs, there is emerging demand for secondary and tertiary supply chain nodes. Pakistan’s geographic location near the Arabian Sea, proximity to Gulf energy markets, and access to western China and Central Asia provide latent logistical advantages. If coupled with regulatory predictability and export facilitation reforms, Pakistan could position itself as a supporting node in fragmented supply chains rather than a primary manufacturing hub.
The energy transition further complicates and reshapes this landscape. As global economies shift toward renewable energy and electrification, demand for critical minerals, grid infrastructure, and energy logistics is increasing. Pakistan’s potential role in this transition remains underdeveloped but strategically relevant. The intersection of energy corridors, particularly linking Gulf hydrocarbons with Chinese industrial demand, places Pakistan in a structurally significant geography. Yet realizing this potential requires institutional coherence and infrastructure synchronization that currently remains incomplete.
The financial dimension of fragmentation is equally consequential. Rising global interest rates, tighter liquidity conditions, and selective capital flows have intensified pressure on emerging economies with high external debt exposure. Pakistan’s recurring reliance on external stabilization mechanisms has placed it within a constrained policy space where fiscal autonomy is increasingly conditional. In a fragmented financial world, access to capital is no longer universal; it is stratified by creditworthiness, geopolitical alignment, and reform credibility. This has implications not only for macroeconomic stability but also for long-term development planning.
Within this evolving environment, Pakistan’s strategic challenge is not simply integration into global trade, but adaptation to its fragmentation. The old model of broad-based globalization, where economies could simultaneously access all markets under uniform rules, is no longer operative. Instead, states must now navigate overlapping economic spheres with distinct regulatory, technological, and political logics. For Pakistan, this requires a recalibration of industrial policy, export strategy, and investment facilitation frameworks.
One emerging pathway lies in regional economic embedding. As Eurasian connectivity expands and Gulf economies diversify beyond hydrocarbons, Pakistan has the potential to serve as a transit and intermediate processing hub. However, this requires consistent policy execution, reduced logistical friction, and alignment between domestic industrial incentives and external demand structures. Without these adjustments, geographic advantage alone will not translate into economic transformation.
Ultimately, the fragmentation of global trade is not a temporary disruption but a defining structural feature of the emerging international economic order. For Pakistan, it represents both a narrowing of traditional globalization pathways and an opening for strategic repositioning within alternative economic architectures. The outcome will depend less on external shifts and more on internal coherence, particularly the ability to translate geography into economic functionality, and alignment into sustained competitiveness in a world where trade is increasingly shaped by security rather than efficiency.
A Public Service Message