
Pakistan’s Remittance Economy Needs a Productive Finance Architecture

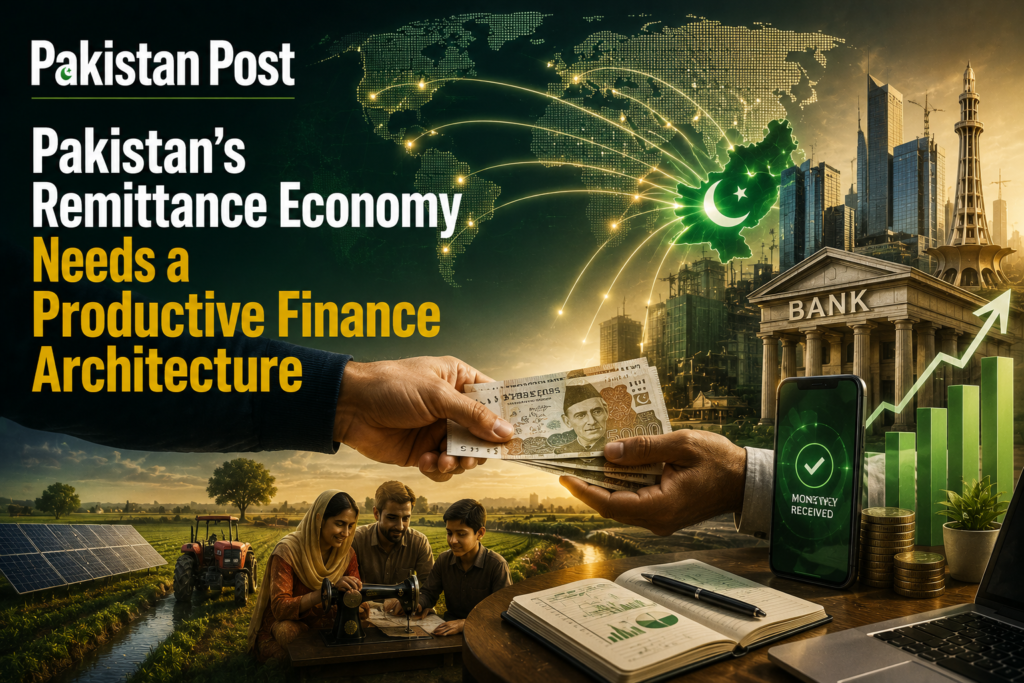
Pakistan’s remittance economy is often discussed as a foreign exchange story. That description is accurate but strategically incomplete. Remittances are one of the country’s most dependable external financing streams, yet their deeper economic significance lies in the financial relationship they create between millions of Pakistani households and the international economy. Money sent by overseas Pakistanis does more than supplement household income. It can determine whether a family remains outside the formal financial system, acquires property, finances education, starts a small enterprise, purchases insurance, accumulates savings or becomes a long term investor. The policy question is therefore no longer simply how Pakistan can attract more remittances. It is how the financial system can convert a portion of those flows into voluntary, secure and commercially credible domestic capital without undermining the household purpose for which remittances are sent.
Pakistan has repeatedly demonstrated an ability to attract large remittance inflows during periods of economic stress. Overseas Pakistanis respond to family obligations, exchange rate movements, economic uncertainty at home and conditions in host countries. Their transfers have provided an important buffer for the balance of payments and helped households absorb inflation, unemployment, health expenditure and educational costs. Yet the same resilience exposes a structural weakness. Remittances are predominantly organised around household liquidity rather than capital formation. The recipient receives money, pays immediate expenses, preserves some cash, purchases gold or property, or deposits funds in a conventional account. The financial system often ends where the remittance arrives.
This is not principally a cultural failure. It is a market design problem.
A household receiving a monthly transfer cannot be expected to behave like an institutional investor. Its priorities are immediate and rational. Food, rent, school fees, healthcare, debt repayment and housing security take precedence over an uncertain business venture. Even where disposable funds exist, confidence in investment institutions remains uneven. Small savers face limited access to appropriately designed products, insufficient financial advice, cumbersome documentation and concerns about liquidity. Informal savings mechanisms survive because they are familiar and socially embedded, while formal investment products frequently appear designed for financially sophisticated customers rather than families receiving regular transfers from abroad.
The central policy challenge is therefore to create an intermediate layer between consumption and conventional investment. Pakistan needs financial products that recognise the characteristics of remittance households: irregular income patterns, modest investment capacity, strong liquidity requirements, low tolerance for loss and a preference for tangible security. Digital finance can provide the infrastructure for such a transition, but technology alone will not solve the problem. A digital wallet that merely receives and transfers money is not a productive finance system. The strategic objective should be a digital financial architecture capable of allowing households to allocate small, voluntary portions of remittance income towards savings, insurance, enterprise finance and regulated investment.
The distinction matters because an aggressive mobilisation strategy could easily become counterproductive. If the state begins treating remittance recipients primarily as a source of investible foreign exchange, it risks reproducing the very mistrust that limits formal financial participation. Overseas Pakistanis are citizens and economic stakeholders, not a balance of payments instrument. Their confidence must be earned through transparency, predictable regulation, competitive returns, effective consumer protection and credible mechanisms for repatriating or liquidating investments.
A practical architecture could begin at the point where the remittance enters the formal system. Banks and regulated digital financial institutions could offer customers a voluntary allocation mechanism, allowing a predetermined percentage of each incoming transfer to remain available for household expenditure while another portion is automatically transferred into a savings or investment pocket. The customer should be able to modify or suspend the allocation at any time. Such a mechanism would use behavioural finance without coercion. The purpose would not be to restrict household consumption, but to make productive saving the path of least resistance for families that can afford it.
The products offered through this system would need to be substantially different from generic investment accounts. A remittance linked savings account could combine immediate liquidity with an enhanced return for maintaining a defined balance. A family protection product could connect regular remittance receipts with affordable life, health or property insurance. A small enterprise facility could use the demonstrated regularity of remittance inflows as one component of a credit assessment, enabling recipients to access working capital without relying entirely on conventional collateral. A digital investment account could provide access to government securities, regulated money market funds, Islamic investment instruments and carefully supervised equity products according to risk tolerance.
Such products would also address a major weakness in Pakistan’s financial system: the absence of a credible savings ladder for lower and middle income households. The financial journey should not require a family to move directly from cash to a sophisticated investment portfolio. It should provide incremental stages. A household could begin with an emergency savings balance, add insurance protection, accumulate a small investment position and eventually qualify for business financing. The objective is financial deepening through gradual participation rather than financial engineering imposed from above.
The banking sector has an important role, but it cannot be the only institutional actor. Digital banks, payment companies, microfinance institutions, asset managers, insurance companies and regulated fintech platforms should be permitted to compete for remittance linked savings. Interoperability would be essential. A customer should not lose access to accumulated savings simply because the remittance arrives through a different regulated channel. The State Bank of Pakistan would need to establish clear standards for product disclosure, customer consent, data portability, fraud prevention and dispute resolution, while allowing commercial institutions sufficient space to develop differentiated products.
The regulatory challenge is particularly significant for overseas Pakistanis. Many expatriate citizens encounter a financial environment that is fragmented between banking procedures in host countries and documentation requirements in Pakistan. Know Your Customer requirements, tax documentation, account opening procedures, power of attorney arrangements, inheritance questions, investment repatriation and property verification can turn apparently simple transactions into lengthy administrative processes. Compliance requirements are necessary, particularly because remittance channels intersect with anti money laundering and counter terrorist financing obligations. But compliance should distinguish between legitimate risk management and unnecessary procedural friction.
A modern remittance policy should therefore establish a single digital identity and documentation architecture for overseas Pakistanis. Once a customer has been adequately verified through approved channels, repeated transactions and investment activity should not require the recreation of the same documentary trail. Regulators should develop interoperable verification standards across banks, investment companies, insurance providers and government securities platforms. This would reduce transaction costs while improving the quality of financial surveillance.
The strategic value of such a system extends beyond individual households. Pakistan has a large overseas population distributed across the Gulf, Europe, North America and other labour markets. Their investment preferences are heterogeneous. Gulf based workers may have different income profiles and liquidity requirements from highly skilled professionals in Europe or North America. The state should therefore avoid a single diaspora product marketed indiscriminately to all expatriates. Product design should reflect income levels, investment horizons, religious preferences, risk appetite and the regulatory environment of the host jurisdiction.
Diaspora bonds could form part of this architecture, but they should not be treated as a substitute for credibility. A government cannot repeatedly approach expatriates for foreign exchange during periods of fiscal stress and expect them to become long term investors without addressing the institutional risks that influence their decisions. Diaspora bonds should have transparent use of proceeds, independent reporting, defined maturities, credible pricing and clear repayment arrangements. Where proceeds are earmarked for infrastructure, energy, export capacity or technology, investors should be able to monitor implementation rather than receiving broad assurances about national development.
There is also a case for investment vehicles specifically connected to productive sectors. Instead of asking an overseas Pakistani to invest directly in an unfamiliar company, regulated funds could pool smaller contributions and finance diversified portfolios of export oriented small and medium enterprises, logistics infrastructure, renewable energy projects, technology firms or industrial supply chains. Professional management and disclosure would reduce the information disadvantage faced by individual investors. The state’s role should be to establish governance standards and reduce systemic risk, not to select commercial winners.
Small business finance deserves particular attention. A significant share of remittance capital already enters entrepreneurial activity, but often through informal arrangements. Families finance shops, transport businesses, agricultural activity, workshops and property based enterprises using accumulated household savings. The problem is not an absence of entrepreneurial intent. It is a shortage of mechanisms that can convert family capital into scalable enterprise finance. A remittance linked credit score, based on transaction history and verified cash flows, could provide lenders with a better assessment of repayment capacity. This would be especially valuable for businesses that remain too small for conventional corporate lending but too established for informal microfinance.
The approach would also help reduce the excessive attraction of residential property as the default investment for overseas Pakistanis. Property appears secure because it is tangible, socially understood and perceived as a hedge against inflation. Yet when excessive savings move into land and speculative real estate rather than productive enterprise, the economy gains assets without necessarily gaining productive capacity. A competitive financial system should offer credible alternatives. If a regulated investment fund can provide transparent ownership, predictable reporting, reasonable liquidity and professionally managed returns, the relative appeal of unproductive property accumulation can gradually decline.
Digital finance can strengthen this transition through automated savings. A remittance recipient could establish a standing rule under which a modest share of every incoming transfer moves into an emergency fund, insurance premium, government security or investment account. Artificial intelligence could eventually assist with personalised financial recommendations, but automated advice must remain subject to suitability rules and human oversight. The objective should be financial inclusion, not algorithmic selling. Products should be matched to the customer’s capacity and risk profile rather than maximising fee generation.
Consumer protection will determine whether the model succeeds. Digital financial expansion without institutional safeguards could simply create new channels for fraud, mis-selling and unauthorised transactions. Remittance recipients, particularly those with limited financial literacy, need clear disclosure of fees, risks, expected returns and withdrawal conditions. Complaints should be resolved through a centralised and time bound mechanism. Digital platforms should maintain strong authentication, transaction monitoring and fraud detection while ensuring that legitimate customers are not repeatedly blocked by poorly calibrated risk systems.
The government should also reconsider the fiscal treatment of diaspora investment. Tax policy should encourage long term productive investment without creating artificial loopholes that invite evasion. Incentives should be linked to investment behaviour rather than merely to the source of funds. A five year investment in an export oriented enterprise, for example, has a different economic value from short term speculative property trading. Policymakers should therefore examine differentiated treatment for investments that generate employment, exports, technological capability or formal business activity, while maintaining transparent eligibility rules.
The most important institutional change would be to move from a remittance mobilisation policy to a remittance conversion policy. Mobilisation asks how much money enters the country. Conversion asks what economic capacity is created after the money arrives. That shift would alter the responsibilities of financial regulators, banks, investment managers and economic ministries. The relevant performance indicators would no longer be limited to remittance volume. Policymakers should monitor the proportion entering formal accounts, the share retained as savings, the value invested in regulated products, the number of remittance linked businesses financed, insurance penetration among recipient households, investment retention periods and the contribution of diaspora capital to exports and employment.
This approach also has implications for national economic resilience. Pakistan’s external account remains vulnerable because foreign exchange inflows are frequently consumed by imports, debt servicing and other external obligations. Remittances provide valuable liquidity, but their developmental contribution increases when part of the associated household wealth becomes durable domestic capital. A deeper savings base could improve financial intermediation, broaden the investor population and reduce excessive dependence on short term external financing.
The strategic establishment should view this as a financial security issue as much as an economic reform. A country that relies heavily on expatriate transfers but offers weak mechanisms for converting household savings into productive investment is leaving a substantial reservoir of national capital underutilised. At the same time, an attempt to capture that reservoir through administrative pressure would undermine trust. The state must therefore create conditions under which households voluntarily conclude that formal productive investment is safer, simpler and more rewarding than holding cash, gold or speculative property.
Pakistan does not need to persuade overseas citizens to sacrifice household welfare for national development. It needs to make household welfare and national development more compatible. When a family can pay its monthly expenses, maintain an emergency reserve, protect itself against financial shocks and automatically invest a modest portion of every remittance in a transparent productive instrument, the distinction between private security and national capital formation begins to narrow.
The objective should ultimately be a remittance economy in which foreign earnings do not simply finance consumption after crossing Pakistan’s borders. They should be capable of becoming savings, insurance, enterprise capital, securities and productive assets while remaining under the control of the households that earned and received them. That requires trust more than slogans, competition more than administrative targets and regulatory certainty more than promotional campaigns. If Pakistan can build that architecture, remittances could evolve from a defensive shield against external financing pressure into one of the country’s most decentralised sources of domestic capital formation.
A Public Service Message